
High Mortgage Rates
Interest rates look to be peaking globally, and in the UK mortgage lenders are already starting to reduce their rates. But we have become used to incredibly low rates since the financial crisis 15 years ago. So this feels expensive even though from 1995 until 2022, the average mortgage interest rate in the UK averaged 5.62%.
However, lots of people have seen the cost jump up dramatically, and at the same time many investors have had a disappointing year with Russian foreign policy and high inflation stifling investment returns.
So many are asking, is it now better to put money towards the mortgage instead?
Like most financial questions, the answer depends on your own circumstances but for most people, the answer is ‘NO!’, and here’s why.
Mortgage or Investment?
Instinctively we want to be debt free, so everyone wants to repay their mortgage as soon as possible. Repaying the known quantity of a mortgage might also feel attractive compared to the uncertainty of an investment, but it doesn’t always make financial sense to throw everything at this.
The returns from the US and UK stock markets over the last 20 years have averaged much more than mortgage interest:
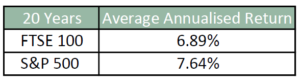
Let’s use an example of a £200,000 mortgage, over 30 years, and £300 per month available to overpay or to invest.
Overpayments would take 11 years off the mortgage term, and save £67,740 in interest.
But investing with an average annual return of 8% would provide a lump sum of £159,410 over the same time; enough to pay off the mortgage and have £52,350 left over:

On top of this, every mortgage payment ties more money up in property, but it is important to have accessible reserves too. This can also have a detrimental effect if there is a property crash where any money overpaid would effectively be lost.
Finally, inflation is actually a good thing for mortgages over the long term. Every year, the mortgage debt loses value to inflation as well as through repayments, whereas money invested continues to grow
Lots of our international clients have property in the UK and locally but the position is the same wherever you are.
In the UK the average house price is £265,100 compared to £69,757 in 1998. In Switzerland for example, the average price has doubled to CHF 1.2m in the same period. You can see that a mortgage debt that might have felt enormous in 1998 doesn’t necessarily now, so the equivalent money invested over the same term would be worth far more.
Should I Invest or Repay My Mortgage?
So for most people, investing is likely to be the best option, but a detailed cashflow and financial planning exercise can determine what is most sensible for you. You can speak to one of our Financial Planners here https://gag-ltd.com/contact/.